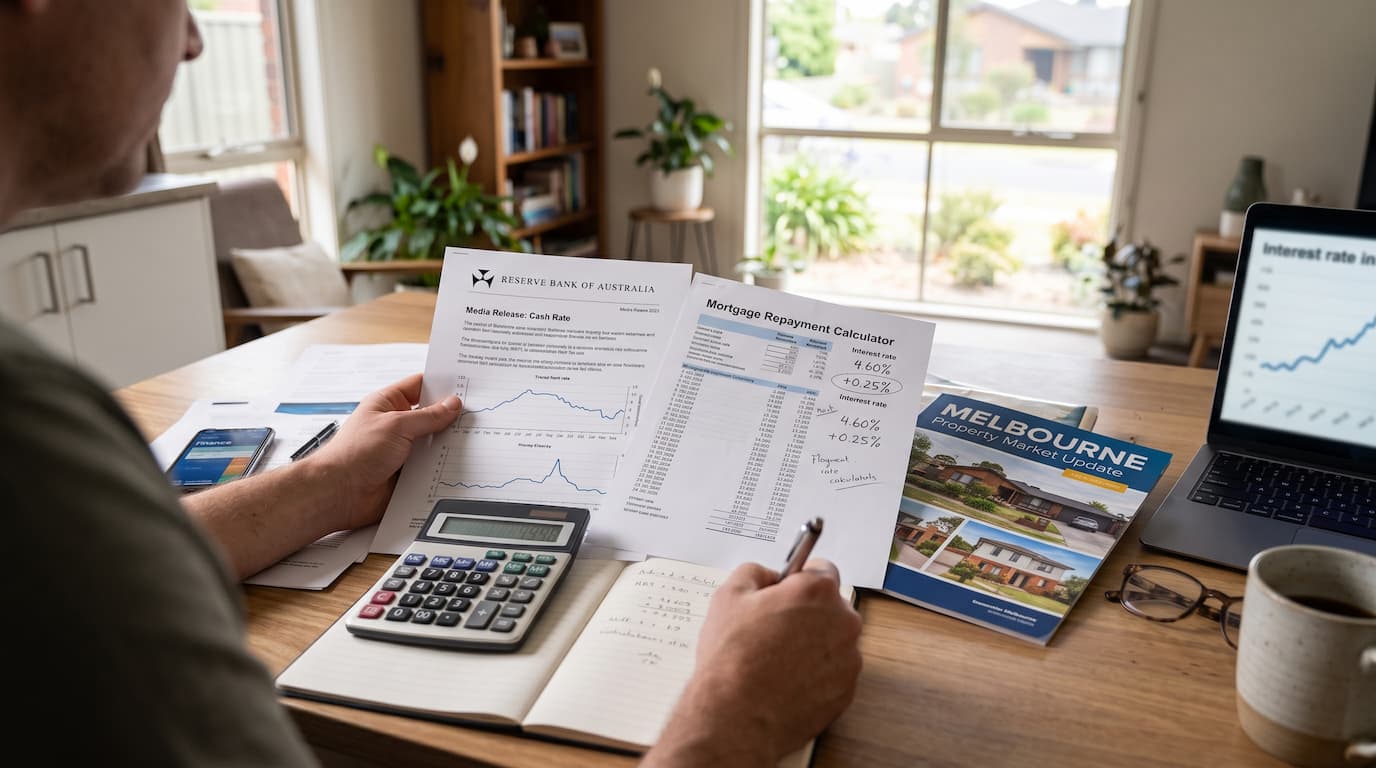
Higher interest rates from the Reserve Bank of Australia (RBA) are likely to put more pressure on Melbourne’s cooling property market by reducing borrowing capacity and increasing repayments. The impact will differ between property investors, depending on how much debt they carry and how much equity they hold.
Key Takeaways
- All of Australia’s Big Four banks are now aligned in forecasting another interest rate hike before the end of the year.
- Melbourne’s housing market is already cooling, with three consecutive monthly declines in local property values.
- An additional 25-basis-point increase will further compress consumer borrowing capacity.
- Investors carrying high variable rate debt will come under immediate cash flow pressure.
- Strategic investors with little debt may find opportunities to buy high-quality property in a soft market.
Is Another RBA Interest Rate Hike Likely?
The Reserve Bank of Australia (RBA) looks likely to increase the official cash rate at its upcoming meeting on 29 September 2026, posing a direct challenge to Melbourne’s cooling property market and shifts for local property investors.
Following recent economic indicators and hawkish statements from central bank officials, the previous consensus of interest rates peaking has shattered.
For Melbourne property owners, buyers, and investors, understanding this imminent shift is crucial for navigating the final months of the spring selling season.
Despite three interest rate increases already delivered earlier this year, core inflation remains stubbornly entrenched outside the central bank’s target zone.
What Are the Big Four Banks Forecasting?
All of Australia’s Big Four banking institutions have revised their predictions and are now fully aligned in forecasting another interest rate hike before the end of the year.
While the Commonwealth Bank of Australia (CBA), ANZ, and Westpac project the official cash rate to rise from its current 4.35 per cent to 4.60 per cent at the November meeting, the National Australia Bank (NAB) predicts the RBA will move as early as September 29.
With the interbank futures market currently pricing in roughly a 60 to 66 per cent probability of a September hike, property market stakeholders need to be prepared for higher borrowing costs.
What Will Be the Impact on the Melbourne Property Market?
Another interest rate hike will hit a Melbourne housing market that is already showing clear signs of cooling and underperforming relative to other capital cities.
- Three consecutive monthly declines in local property values have highlighted how sensitive the Victorian capital has become to sustained monetary tightening.
- According to the spring auction report featured by The Australian, Melbourne recorded a clearance rate of just 52 per cent against 70 per cent a year ago.
An additional 25-basis-point increase will further compress consumer borrowing capacity. This reduction in purchasing power means that the seasonal spring influx of property listings will face a thinner pool of highly qualified buyers, likely accelerating the modest downward trend in Melbourne dwelling prices over the next 12 months.
What Will Be the Impact on Property Investors?
Melbourne investors are operating in a very challenging regulatory and financial environment.
Alongside higher interest rates, recent Victorian state investor tax changes, such as lowered land tax thresholds, have already prompted a significant withdrawal of rental providers from the residential market.
A fourth rate hike for 2026 will compound mortgage repayment pressures and directly impact net rental yields.
Will Higher Interest Rates Affect Every Property Investor the Same Way?
The end result will be different depending on whether you’re a heavily leveraged investor or a strategic buyer with a lot of equity.
- Investors carrying high variable rate debt will come under immediate cash flow pressure and it may lead to those without enough buffer to be forced to offload some properties adding more stock to the market.
- For strategic investors unburdened by too much debt, the soft market conditions in Melbourne present a unique opportunity to purchase high-quality property at a great price with high capital growth potential down the track as the market recovers.
Review Your Property Finance With Perry Finance
Every borrower’s situation is different, so it is worth understanding how higher borrowing costs could affect your own loan before making any property decisions.
Perry Finance is a mortgage broking business with a strong Melbourne focus, helping home buyers and property investors with their lending. To discuss your options, contact Perry Finance today.