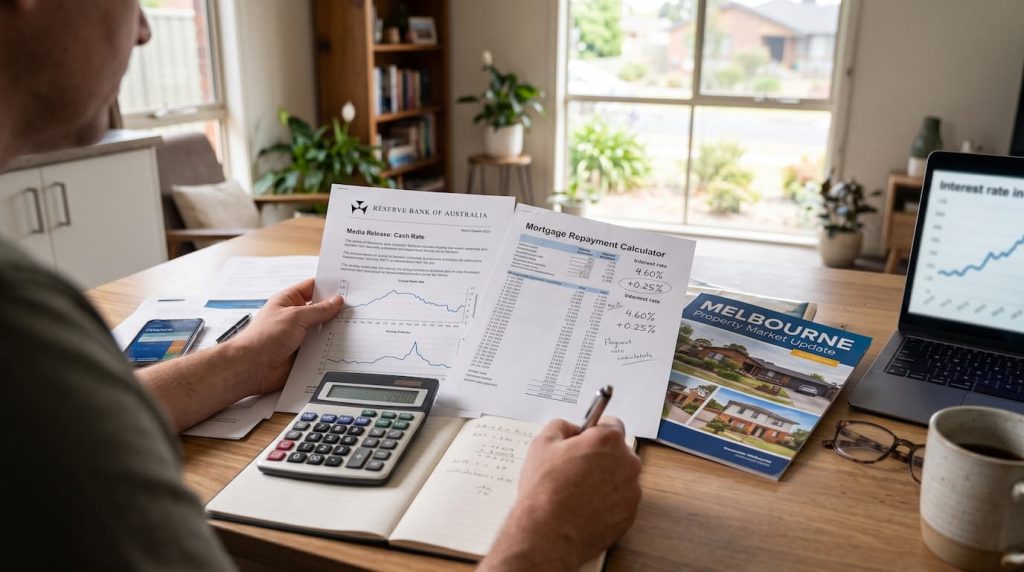
Money markets now see a 25-basis-point rate hike on Melbourne Cup Day, Tuesday 3 November 2026, as the likely outcome after inflation rose to 4.3 per cent. A move to 4.85 per cent would cut buyers’ borrowing power further, squeeze investor cash flow and add pressure to a sliding Melbourne market.
Key Takeaways
- Headline inflation rose to 4.3 per cent in the 12 months to September 2026, with trimmed mean inflation at 3.6 per cent.
- A 25-basis-point hike on 3 November 2026 would lift the cash rate from 4.60 per cent to 4.85 per cent.
- Each rate rise reduces a buyer’s maximum borrowing capacity, because banks assess loans with a 3 per cent buffer.
- Melbourne’s median house price fell 3.3 per cent in the September quarter, giving patient buyers more room to negotiate.
- A higher cash rate will push many neutral investment properties into negatively geared territory.
Why Is a Cup Day Rate Hike Now the Favourite?
Melbourne property buyers and owners are bracing for a potential fifth interest rate hike of the year on Melbourne Cup Day, a move that could accelerate the city’s current real estate downturn.
The Australian Bureau of Statistics (ABS) has revealed that headline inflation accelerated to 4.3 per cent in the 12 months to September 2026. More critically, the Reserve Bank of Australia’s (RBA) preferred underlying measure of trimmed mean inflation has crept up to 3.6 per cent.
This lands well above the RBA’s target band of 2–3%, shattering hopes of a near-term reprieve.
Following the data release, financial money markets rapidly adjusted, with Bloomberg data showing the priced-in probability of a 25-basis-point hike on Tuesday, 3 November 2026, surging big time.
What Would a 4.85 Per Cent Cash Rate Mean for Melbourne?
If Governor Michele Bullock and the board pull the trigger, the official cash rate will jump from 4.60 per cent to a restrictive 4.85 per cent, marking its highest level since the 2008 Global Financial Crisis.
For a Melbourne property market that has already been sliding for six consecutive months, this looming announcement could represent a significant turning point.
How Would Another Hike Affect First Home Buyers?
For hopeful Victorian first-time buyers, another interest rate hike directly impacts borrowing power rather than just increasing monthly payments.
However, the unique state of the local market means a distinct window of opportunity is opening.
Every 25-basis-point increase slashes a buyer’s maximum borrowing capacity. For a typical dual-income household, a fifth hike this year means loan limits will contract even further.
Banks evaluate loan applications using a strict 3 per cent buffer. As actual variable rates climb toward 7.5 percent, the buffer forces buyers to qualify at hypothetical repayment rates above 10 per cent.
The major silver lining for local buyers is that Melbourne’s median house price dropped by 3.3 per cent in the September quarter to $1,014,335, putting it on track to fall below the $1 million mark by the end of the year.
Total listings across the city are up 23 per cent compared to this time last year, and properties are averaging 39 days to sell (up from 23 days). Reduced competition from highly leveraged buyers gives patient first home buyers significant room to negotiate lower purchase prices.
How Would Property Investors Be Affected?
Melbourne property investors face a challenging landscape where the mathematics of maintaining a local portfolio are shifting.
Four rate hikes so far in 2026 have already severely impacted weekly cash flows. Moving to 4.85 per cent will push many historically neutral properties deeply into negatively geared territory.
Landlords are also navigating Victoria’s recent property tax changes. A recent Property Council survey showed that over 80 per cent of respondents link these state levies directly to dampening buyer confidence and rising housing costs.
Because detached houses remain expensive, affordable entry-level units and apartments under $1 million are experiencing increased competition and attracting more investors.
Check Your Borrowing Capacity Before the Next Rate Move
A Melbourne Cup Day rate rise would serve as a stark reminder that the RBA remains entirely focused on breaking stubborn domestic inflation. For Melbourne buyers, sellers, or anyone looking to refinance before the end of the year, it makes it imperative to get a certified assessment of your borrowing capacity.
Every borrower’s income, expenses and goals are different, so the impact of a rate rise will vary from household to household.
Perry Finance helps Melbourne home buyers, property investors and businesses find the right finance for their goals. To discuss your options, contact Perry Finance today.